
By WilliamMarkDesigns | Atlanta Home Builder & Developer
If you've been thinking about buying a new home in Atlanta but feel like you need a finance degree just to figure out if you can afford it — this post is for you.
We're going to walk through the actual numbers: what income lenders want to see, how much you need saved before you start, what your monthly payment will look like, and what first-time buyer programs exist to close the gap.
None of this is financial advice. But it is the honest, detailed picture that most builder websites skip over — and that you deserve to have before you start shopping.
First: What Lenders Are Actually Looking At
When a lender reviews your application, they're running a few key calculations. Understanding these ahead of time puts you in control of the conversation.
Debt-to-Income Ratio (DTI)
This is the number that makes or breaks most applications. Your DTI is your total monthly debt payments divided by your gross monthly income. Most conventional lenders want to see a DTI at or below 43–45%. FHA loans can go higher — up to 50% in some cases — but the lower your DTI, the better your rate.
Monthly debts lenders count: your future mortgage payment (principal + interest + taxes + insurance), car payments, student loans, credit card minimums, and any other installment debt. They do not count utilities, groceries, or subscriptions.
Credit Score
Conventional loans typically require a minimum score of 620, though you'll get the best rates at 740 and above. FHA loans go down to 580 with 3.5% down, or as low as 500 with 10% down. If your score is below 680, it's worth spending 6–12 months improving it before applying — the difference in interest rate between a 660 and a 740 score can add up to tens of thousands of dollars over the life of a loan.¹
Employment and Income Stability
Lenders want to see two years of consistent income history. W-2 employees have the easiest path. Self-employed buyers can qualify, but typically need two years of tax returns showing stable or growing income, and lenders will use the lower of the two years. If you're self-employed and write off a lot of expenses, talk to a mortgage broker before assuming your stated income is what they'll use — it often isn't.
How Much Do You Need Saved?
This is the question we hear most often. The answer has more parts than people expect.
Down Payment
This is the piece most buyers focus on, and it varies by loan type:
Conventional loan: 3–20% down. Less than 20% triggers PMI (private mortgage insurance), which runs roughly 0.5–1.5% of the loan per year and gets added to your monthly payment until you reach 20% equity.
FHA loan: 3.5% down with a 580+ credit score. Comes with mandatory mortgage insurance premiums (MIP) for the life of the loan if you put less than 10% down.
VA loan: 0% down for eligible veterans and active-duty service members.
USDA loan: 0% down for qualifying rural and suburban areas — some parts of metro Atlanta qualify, though intown neighborhoods typically don't.
For a new construction home at WilliamMarkDesigns, we use the Georgia Association of Realtors New Construction Form and collect a 5% construction deposit at contract, which is applied toward your down payment at closing. This is worth knowing when you're calculating how much to have liquid before you go under contract.
Closing Costs
Buyers routinely underestimate this. In Georgia, closing costs typically run 2–4% of the purchase price and include lender fees, title insurance, attorney fees (Georgia is an attorney-closing state), prepaid homeowner's insurance, prepaid property taxes, and prepaid interest.² On a $650,000 home, that's $13,000–$26,000 on top of your down payment.
Reserves
Many lenders want to see 2–3 months of mortgage payments remaining in your account after closing — proof that you won't be immediately underwater if something changes. Factor this into your savings target.
What Does the Monthly Payment Actually Look Like?
The purchase price is the number people shop by, but the monthly payment is the number you live with. Here's how to estimate yours before you talk to a lender.
Your total monthly housing payment (what lenders call PITI) is made up of:
Principal and interest — based on your loan amount and interest rate
Property taxes — in Atlanta/Fulton County, roughly 1.0–1.2% of assessed value per year³
Homeowner's insurance — typically $1,200–$2,000/year for a new home in this range⁴
PMI (if applicable) — roughly 0.5–1.5% of the loan amount per year
As of October 2026, 30-year fixed mortgage rates are hovering in the mid-to-upper 6% range for well-qualified buyers.⁵ Rates shift frequently — always get a current quote from a lender rather than assuming.
Estimated Monthly Payment Table
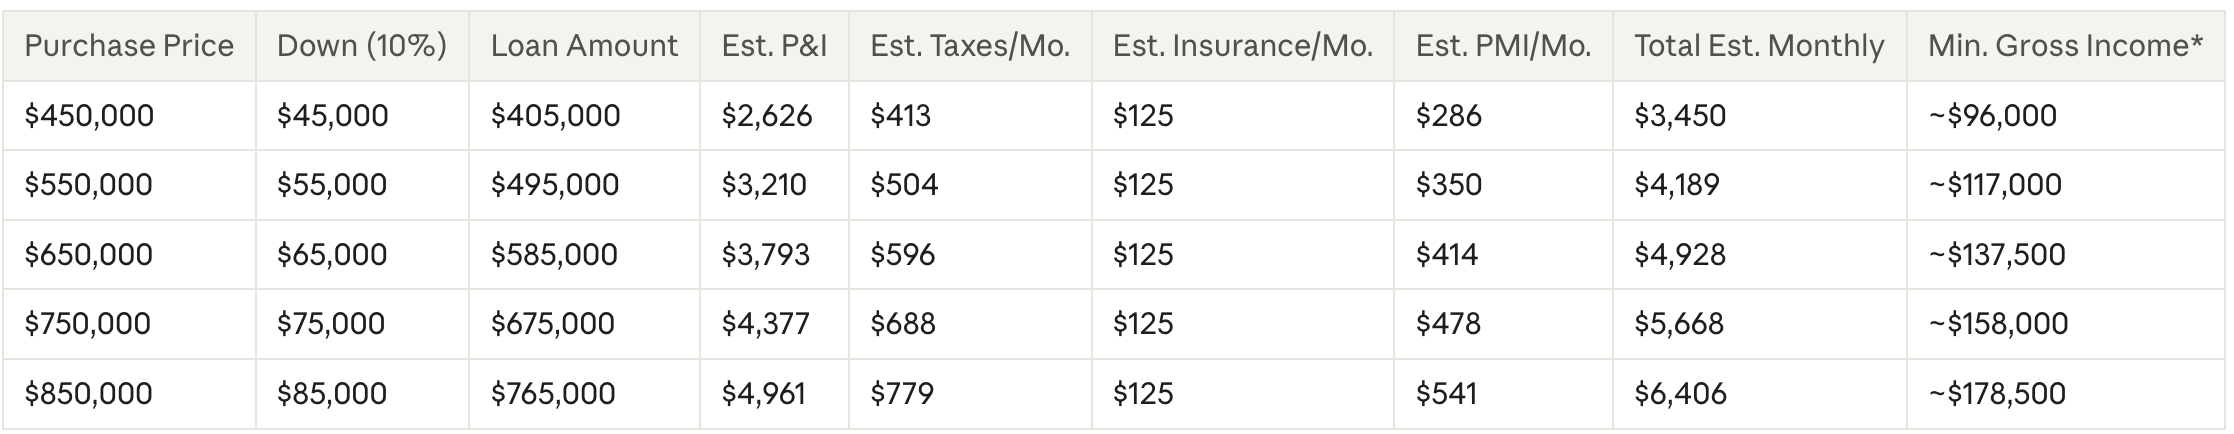
*Minimum gross income assumes total monthly payment equals no more than 36% of gross monthly income, with no other monthly debt obligations.
Assumptions and limitations: This table is for illustrative purposes only and does not constitute financial advice or a loan estimate. Calculations assume: 30-year fixed mortgage at 6.75% interest rate; 10% down payment (conventional loan); PMI at 0.85% of loan amount annually; property tax rate of 1.1% of purchase price annually; homeowner's insurance of $1,500/year; no HOA fees; no other monthly debt. Actual payments will vary based on your credit score, lender, loan type, the county's assessed value, your insurance carrier, and market conditions at the time of application. Rate of 6.75% reflects approximate market conditions as of October 2026 and may change. Always obtain a formal Loan Estimate from a licensed mortgage lender before making financial decisions.
First-Time Buyer Programs Worth Knowing About
Georgia has several programs specifically designed to help first-time buyers close the gap on down payment and closing costs.
Georgia Dream Homeownership Program
Administered by the Georgia Department of Community Affairs, this program offers down payment assistance of $10,000 (or $12,500 for buyers in certain professions including healthcare, education, and public safety). Income and purchase price limits apply.⁶
Atlanta Affordable Homeownership Program
The City of Atlanta offers down payment assistance for qualifying buyers purchasing within city limits. Income limits are based on Area Median Income (AMI) and are updated annually.
Employer-Assisted Housing
Several large Atlanta employers — including Emory, Georgia-Pacific, and Atlanta Public Schools — offer housing assistance programs for employees buying near their workplace. Worth checking with your HR department before assuming you're on your own.
FHA vs. Conventional: Which Is Better for First-Time Buyers?
It depends on your credit score and how long you plan to stay. FHA loans are more accessible but carry permanent mortgage insurance if you put less than 10% down. Conventional loans let you cancel PMI once you hit 20% equity. If your score is above 680 and you can manage 5–10% down, conventional is usually the better long-term call. If your score is between 580 and 679, FHA gets you in the door.
The Timeline Most First-Time Buyers Don't Expect
Here's something nobody tells you upfront: buying a new construction home in Atlanta takes longer than buying a resale — and that's not a bad thing. You're getting a home built to current code, with a builder warranty, and often the ability to choose your own finishes.
A realistic timeline:
3–6 months before: Check your credit, meet with a mortgage lender, get pre-approved, and identify your price range
1–3 months before contract: Tour available homes and pre-sales, review floor plans, ask about remaining finish selections
At contract: Sign the New Construction Agreement, pay your construction deposit (5% at WMD)
During construction: Design meeting, periodic walkthroughs, final blue-tape walkthrough approximately two weeks before closing
At closing: Pay remaining down payment and closing costs, receive keys
For a pre-sale home, the construction timeline varies depending on how early in the build you go under contract — anywhere from 3 to 10 months. For a completed spec home, you can close in a standard 30–45 day window.
What to Do Right Now
If you're not ready to buy today, that's okay. Here's what to do in the meantime:
Pull your credit reports at annualcreditreport.com — free, no credit impact, one report per bureau per year
Calculate your current DTI using your real monthly debts and gross income
Build your savings target — use the table above to estimate what you need at your target price point, then add closing costs (3% is a safe estimate) and 3 months of reserves
Talk to a mortgage lender or broker before you start seriously shopping — a pre-approval letter is required to make an offer
Join our early access list — we announce pre-sales and new listings to that list first, before they go public
If you're ready to explore what's currently available, browse our most affordable listings → or join our early access list to hear about new pre-sale opportunities before they go public.
Questions about the pre-sale process? Contact us or book a custom home consultation and we'll walk you through everything in detail.
Resources
Consumer Financial Protection Bureau — How credit scores affect your mortgage rate (consumerfinance.gov)
Georgia Attorney General's Consumer Protection Division — Closing Cost Guide for Georgia Homebuyers
Fulton County Board of Assessors — Property Tax Information (fultonassessor.org)
Insurance Information Institute — How Much Homeowners Insurance Do You Need? (iii.org)
Freddie Mac Primary Mortgage Market Survey — Weekly Average Rates (freddiemac.com)
Georgia Department of Community Affairs — Georgia Dream Homeownership Program (dca.ga.gov)
